Market Interpretation
Economic Expectations 2026: What’s Next for Greater Boston Real Estate
Two economists at Economic Expectations 2026 agreed on the big picture. Affordability starts to loosen, slowly. Rates will keep moving, Massachusetts is still short on housing, and every town behaves differently. My advice: buyers should budget for a range of rates, not one rate. Sellers should weigh incentives before they cut the price.
Watch: My 90 second recap of Economic Expectations 2026, and the two numbers every buyer and seller should run right now.
I sat in on Economic Expectations, hosted by the Greater Boston Real Estate Board and the Greater Boston Association of REALTORS®. Danielle Hale, Chief Economist at Realtor.com, covered the national picture. Dr. Mark Melnik of the UMass Donahue Institute, the group behind the state’s Housing Needs Assessment, covered Massachusetts. Jody O’Brien opened with an update on the Affordable Homes Act.
I took a lot of notes. Most of them point to the same two questions my clients ask me every week. What should I budget for? And what should I do about it? So I built two tools to answer them, and you will find both further down this page.
Who spoke at Economic Expectations 2026?
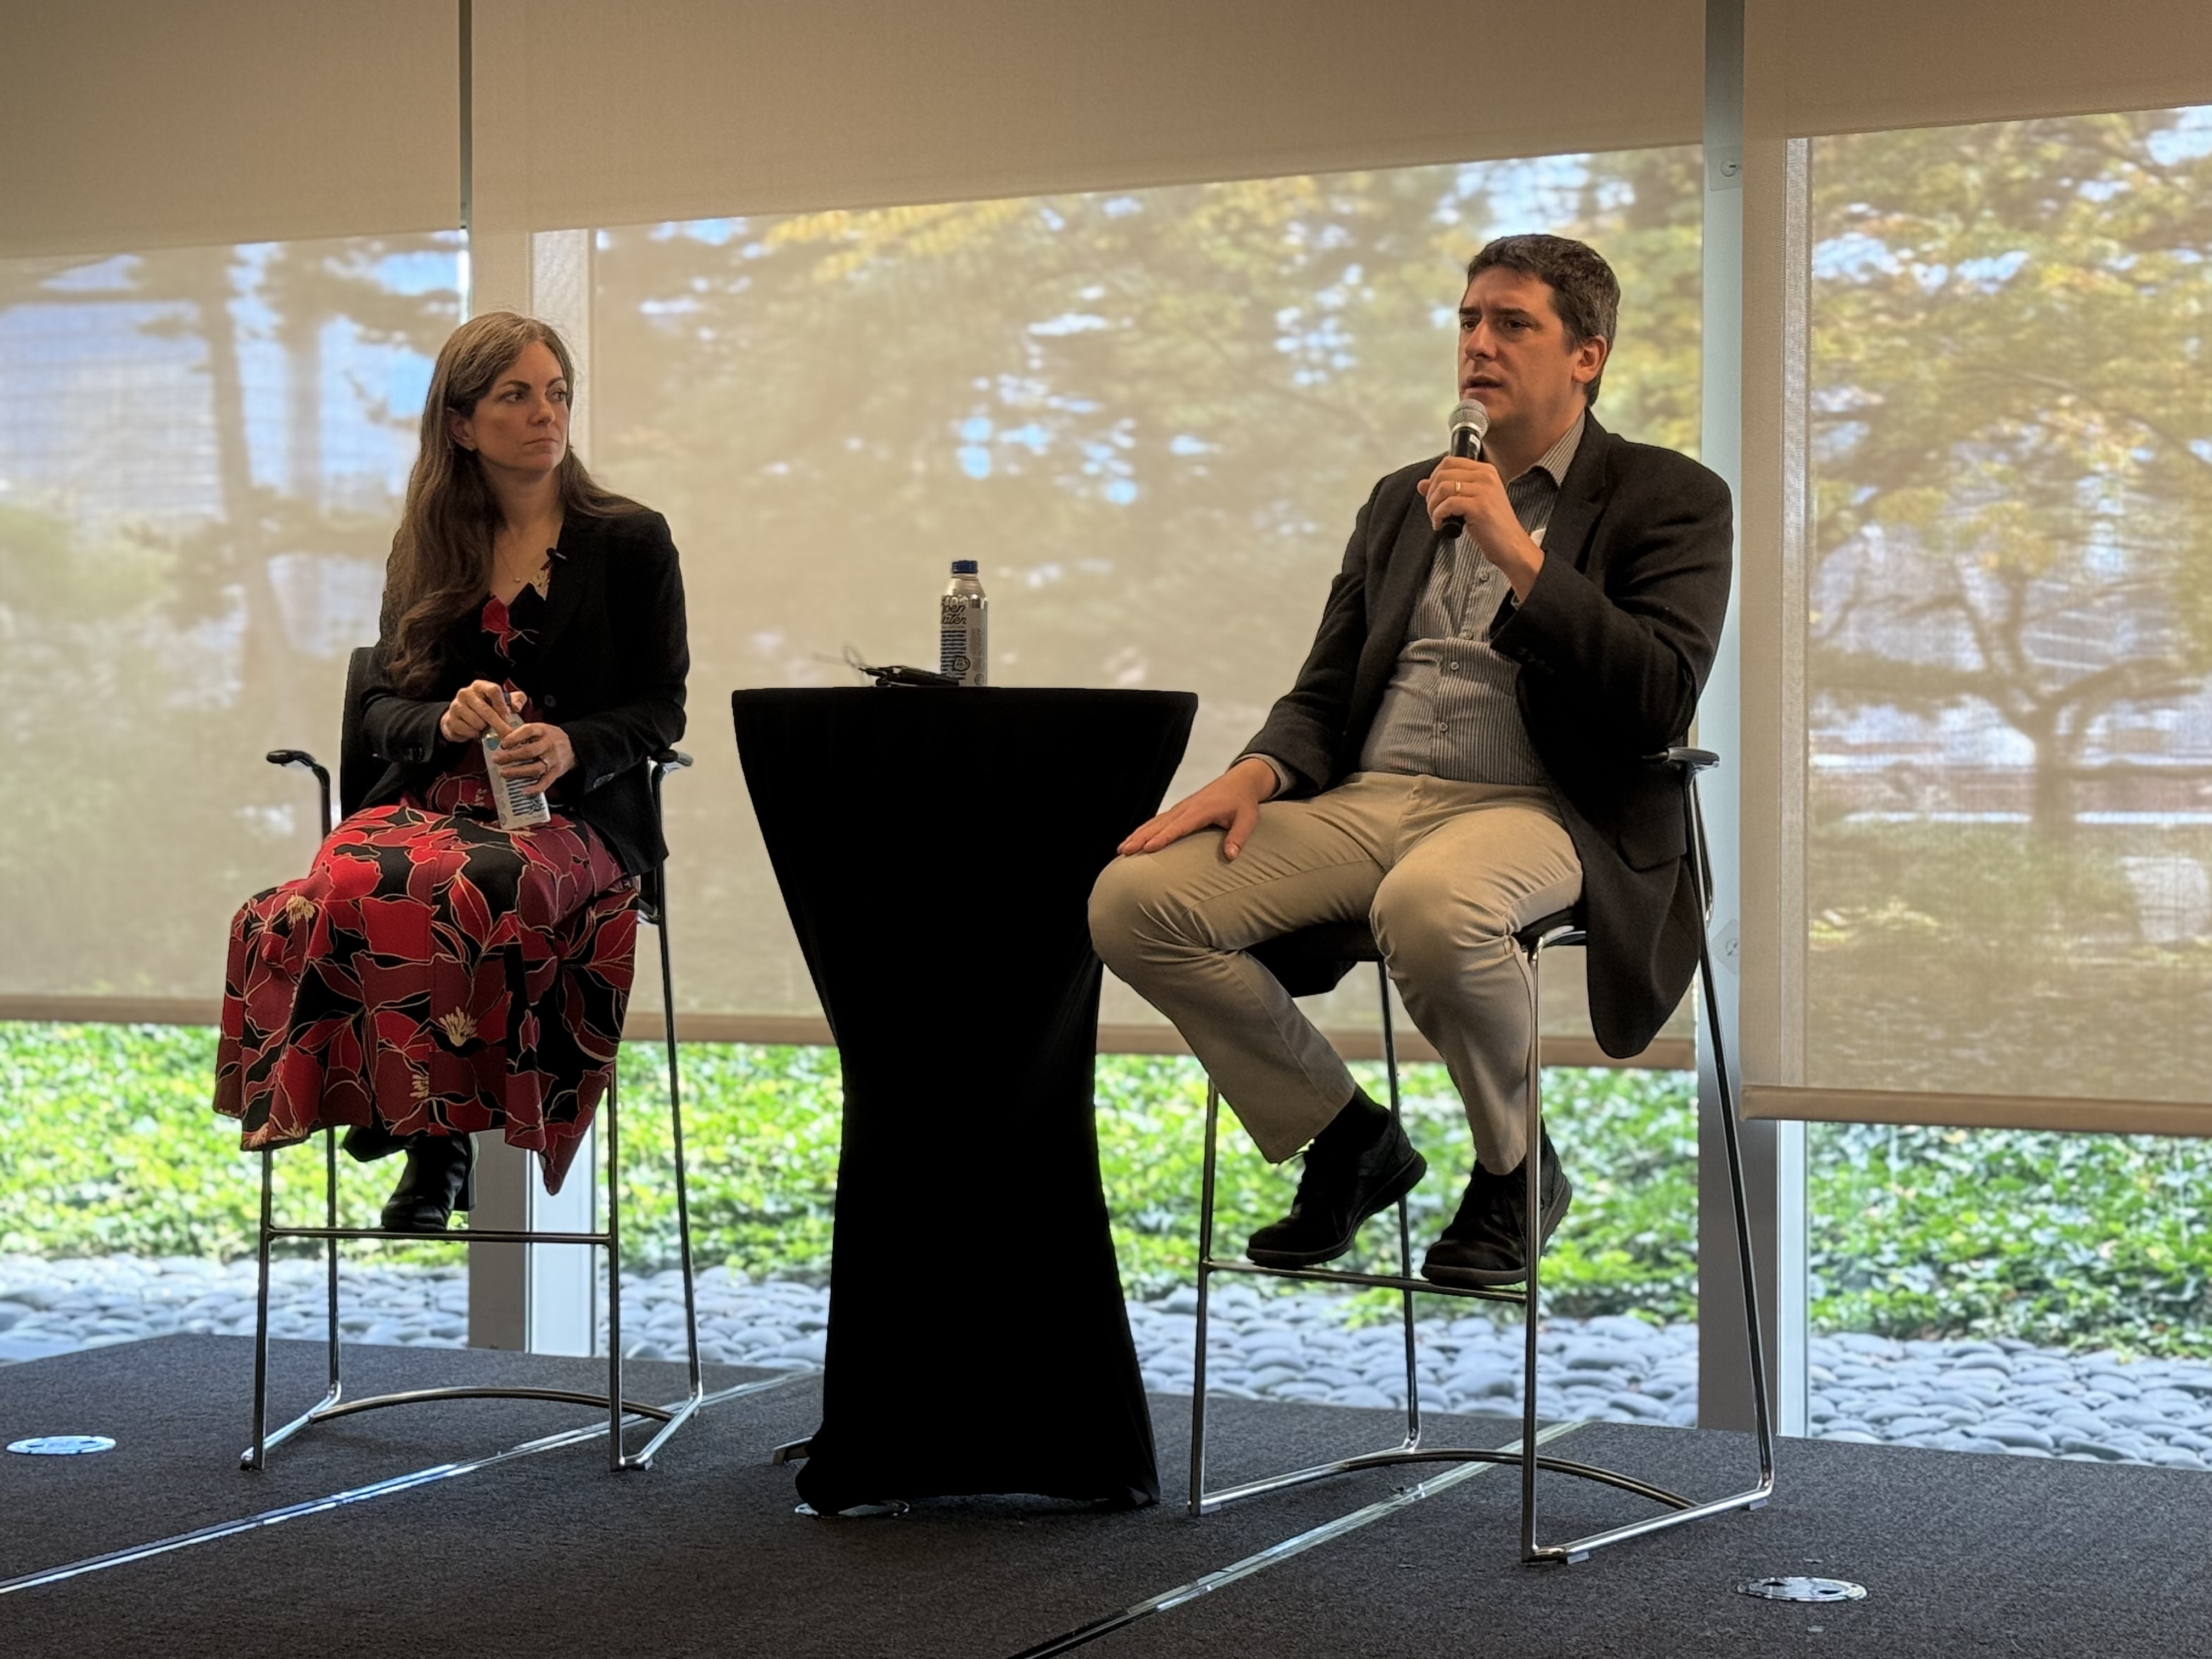
Danielle Hale is Chief Economist at Realtor.com, where she leads the company’s economics team. If you follow housing news, you have probably heard her. She is quoted regularly in The Wall Street Journal, Bloomberg, CNBC and most of the national networks. Before Realtor.com, she spent nearly a decade as an economist at the National Association of REALTORS®, running housing data and research on how policy shapes the market. Her team publishes its work at realtor.com/research.
Dr. Mark Melnik directs Economic and Public Policy Research at the UMass Donahue Institute. His team studies population, income and labor trends across the state, and he is a senior managing editor of MassBenchmarks, published with the Federal Reserve Bank of Boston. Before UMass, he ran research for the Boston Redevelopment Authority. His doctorate focused on the gap between the skills Greater Boston employers need and the skills workers bring. When he talks about Massachusetts, he is talking about his own research.
What did the economists say about the economy?
Nationally, the economy has held up better than expected. Hale pointed to real GDP growth of 2.2%, steady consumer spending, and a labor market that has been more resilient than forecasters thought. The weak spot is inflation. In September, prices rose faster than wages, which means real wages fell. That keeps upward pressure on mortgage rates, and energy prices tied to events overseas are not helping.
Massachusetts tells a stranger story. Melnik showed job growth of just 0.2% from August 2025 to August 2026, and unemployment at 4.3%, now above the national rate. Yet the state’s GDP has kept pace with the country. Massachusetts workers are about 15% more productive than the national average, and research and development drives more than a quarter of the state economy. We produce more with fewer new jobs.
He also pushed back on a popular story. People are not fleeing Massachusetts. The population has grown every year outside of the pandemic. Most of that growth, and about 80% of labor force growth, comes from people moving here from other countries. With the state getting older and immigration slowing, Melnik expects the workforce to shrink over time. That matters for housing, because the people who fill jobs need somewhere to live.
Why should buyers budget for a range of rates?
Because the rate you see today is not the rate you will lock. If you start looking now, you might write an offer in six weeks or six months, and rates can move a long way in that time.
Hale shared research from Realtor.com that turns that uncertainty into numbers. They looked at every move in the 30-year fixed rate since 2000 and measured how far it typically traveled. About 80% of the time, rates moved less than half a point over three months and less than three quarters of a point over six months. That is not a forecast. It is a planning range, and it is the best one I have seen.
| Search length | Rate range | Monthly payment range |
|---|---|---|
| Today | 7.37% | about $5,247 |
| 3 months | 6.87% to 7.87% | about $4,990 to $5,508 |
| 6 months | 6.62% to 8.12% | about $4,864 to $5,640 |
Look at the top of that range. On a six-month search, the same house could cost almost $400 more a month than it does today. If your budget only works at today’s rate, it does not really work. A rate-proof budget is one that still works at the high end. Then, if rates fall, you have room to spare instead of a problem to solve.
Bonus tool. Enter a price, your down payment, and the monthly payment you are comfortable with. Pick how long you expect to search. The tool shows your payment at the low, middle, and high end of the range, and the price that keeps you safe across all of it.
Should sellers cut the price or offer a rate buydown?
Hale noted that active listings are up, sellers are pricing more realistically, and price reductions are ticking up. Builders, who have more new homes to sell, are leaning on incentives and mortgage rate buydowns to get them sold. Resale sellers can use the same tools.
When a buyer hesitates, the instinct is to drop the price. But today’s buyers are not shopping on price alone. They are shopping on the monthly payment. A price cut lowers that payment a little. A buydown, where you pay points that permanently lower the buyer’s rate, can lower it a lot more for the same money.
Here is a hypothetical example on a $950,000 home with a buyer putting 20% down. You decide you are willing to give $20,000. As a price cut, that lowers the buyer’s payment by about $110 a month. Spent on discount points, assuming each point lowers the rate by a quarter point, it lowers the payment by about $336 a month. That is the same relief as cutting the price by roughly $61,000.
A buydown is not always the answer. Loan programs cap how much a seller can contribute. Lenders price points differently, so the rate drop per point varies. A price cut also saves you the commission and Massachusetts tax stamps on that amount, so it costs you slightly less. Some buyers need cash at closing more than a lower payment, and a closing cost credit helps them most. The right move depends on the buyer in front of you, and that is a conversation, not a formula.
Bonus tool. Enter your price and the amount you are willing to give. The tool compares a price cut, a closing cost credit, a permanent buydown, and a 2-1 buydown side by side: the buyer’s payment, cash at closing, total benefit, and what each one really costs you.
Is Massachusetts still short on housing?
Yes, and both economists said so plainly. Nationally, Hale put the shortfall at about 2 million homes. Count the nearly one in three young adults still living with their parents, and the real gap is closer to 4 million. Melnik said Massachusetts has been underproducing for decades. Permits are up from the lows of the Great Recession but nowhere near historic levels.
The state is trying to close that gap. O’Brien walked through the Affordable Homes Act of 2024: more than 60 initiatives, $5.16 billion in spending over five years, and a goal of 222,000 new homes by 2035. Her update counted more than 2,000 accessory dwelling units approved statewide, plus a new $5 million ADU pilot program. Under the Act, ADUs are allowed by right in single-family zones, with no special permit required, though local rules still apply. Melnik offered a counterpoint. He called the state’s figure of 100,000 units in development an exaggeration. Both can be true. The policy is moving, and building still takes time.
Realtor.com put a grade on it. Its September metro report cards scored the 100 largest metros on homebuilding and affordability, and greater Boston got an F. We ranked 96th out of 100. Worcester (93rd) and Providence (99th) failed too, so this is a regional problem, not just a city one. One number stood out to me. New construction in the Boston metro costs about 36% more than existing homes, so even the homes we do build don’t ease affordability much.
Realtor.com pointed straight at the rules. Compared with Austin, which landed near the top, Boston has about four times as many pages of zoning law. Zoning covers 79% of Boston’s land versus 15% in Austin, and parking minimums apply to 88% versus 37%. That lines up with what Melnik said. Our shortage isn’t about land. It’s about what we allow on it.
Supply is also locked up in homes that may change hands over the next decade. Hale shared that 71% of the homes baby boomers are expected to free up have three or four bedrooms. That inventory will come, but gradually.
What does this mean for Belmont and Watertown?
Hale called the Northeast the most balanced region in the country right now. Boston area asking prices are down about 2% from a year ago, though sale prices have held up better. Suburbs are seeing the strongest demand. Still, regional averages only go so far, so here is what our own towns did over the last 90 days.
| Town | Median sale price | Sale to list | Median days to offer |
|---|---|---|---|
| Belmont | $1,545,000 | 98.6% | 15 |
| Watertown | $1,205,000 | 106.1% | 6 |
Two towns that share a border, behaving very differently. Belmont homes are selling a little under list and taking about two weeks to find a buyer. Watertown’s small sample of single-family sales closed above list in under a week. That is exactly why Hale ended her talk by stressing local tools and local expertise. The live numbers for every town I cover sit on my market context page, right next to both tools.
What’s next for the Greater Boston housing market?
The talk set the stage. The data that came out this week fills in the next chapter, and it’s a mixed one.
Rates went the wrong way. The 30-year fixed crossed 7% for the first time since January 2025 and sat at 7.40% in Freddie Mac’s latest reading. September inflation came in hotter than expected, and wages are rising slower than prices. Realtor.com’s baseline now has the Fed holding in October and raising rates again in December. There is one hopeful sign. The 10-year Treasury yield slipped late last week, and if that holds, mortgage rates could ease a little.
Buyers stepped back. Pending home sales fell 7.3% in September, the lowest level in the history of the data. The Northeast held up best, down 4.2% for the month, the smallest drop of any region. Contracts lead closings by a month or two, so expect slower sales numbers through the end of the year.
Nationally, the market is tilting toward buyers. Asking prices have fallen for 11 straight months. More than one in five listings had a price cut in September, a record for this time of year. Inventory is up about 7% from last year. Realtor.com’s Market Clock moved the country to 4 o’clock, a balanced market leaning toward buyers.
Boston is moving the other way. The same Market Clock puts the Boston metro at 9 o’clock, balanced but tightening. In plain English, conditions here are drifting back toward sellers while much of the country drifts toward buyers. Boston also showed up again on Realtor.com’s September hottest markets list. Buyers keep coming here for the jobs, and the housing shortage above hasn’t gone anywhere.
So what does that mean for you? If you are waiting for a national buyer’s market to show up in Belmont or Watertown, it may not come. Rates are the bigger variable, and nobody can promise where they go next. That’s exactly why I built the rate-proof budget tool. Plan for the range, and you are ready whichever way it breaks.
What are the takeaways for buyers and sellers?
If you are buying, build your budget at the top of the rate range, not the middle. Know your number before you fall for a house. Go in clear eyed about renting, too. Hale shared that owning in the Boston metro costs about 57% more than renting right now. That gap is real. It is also only one side of the decision, because rent buys a place to live and a mortgage builds equity. There is always another house. The goal is to be ready when the right one shows up.
If you are selling, price for the market we are in today, and know your incentive options before the first offer arrives. A buyer worried about a monthly payment may respond to a buydown far more than to a price cut of the same size. That is a strategy to plan with your agent and the buyer’s lender, not something to improvise in the middle of a negotiation.
You only know the market you are in. This one rewards preparation.
Let’s run your numbers
The tools give you a starting point. A conversation turns them into a plan for your house, your budget, and your timing.
Schedule a call Open the toolsSources
- Danielle Hale, Chief Economist, Realtor.com, presentation at Economic Expectations 2026, Greater Boston Real Estate Board and Greater Boston Association of REALTORS®
- Dr. Mark Melnik, Director of Economic and Public Policy Research, UMass Donahue Institute, presentation at the same event
- Jody O’Brien, presentation on the Affordable Homes Act of 2024 at the same event
- Realtor.com, rate volatility research, September 23, 2026, based on the Freddie Mac 30-year fixed rate since 2000
- Mortgage News Daily, 30-year fixed rate index, October 16, 2026
- Joel Berner, “Metro Report Cards: Top and Bottom of the Class for Homebuilding and Affordability,” Realtor.com, September 16, 2026. realtor.com/research
- Realtor.com Market Clock Report, 2026 Q3, October 19, 2026
- Hannah Jones, “Pending Home Sales Hit Record Low in September,” Realtor.com, October 20, 2026
- Danielle Hale, Weekly Housing Outlook, Realtor.com, October 19, 2026
- MLSPIN, Belmont and Watertown single-family closed sales, trailing 90 days ending October 16, 2026
Payment figures are estimates of principal and interest on a 30-year fixed loan. Examples are hypothetical. Seller contribution limits and point pricing vary by loan program and lender. This is not financial, tax, or legal advice. Talk to a licensed lender about your own rate and terms.